

Introduction
Money transfer carding represents one of the most lucrative yet technically demanding niches within the carding ecosystem. Unlike traditional goods-based carding, money transfer carding involves directly converting stolen card data into liquid cash through various financial service platforms. In 2026, this practice has evolved significantly, with new security measures and detection systems making it both more challenging and more rewarding for those who understand the nuances.
This comprehensive guide will walk you through everything you need to know about money transfer carding in 2026 from the fundamental concepts and requirements to the specific methods for targeting major services like Western Union, PayPal, Cash App, Remitly, Skrill, and Google Pay. Whether you’re a complete beginner or an experienced carder looking to expand your repertoire, this resource provides the actionable intelligence you need to succeed.
1. What is Money Transfer Carding?
Money transfer carding is the process of using stolen credit card information to send money through digital money transfer services, then collecting that money in a controlled account or through a money mule. Unlike purchasing physical goods, this method directly converts card data into cash, making it one of the most efficient cashout methods available. In 2026, money transfer services have implemented sophisticated fraud detection systems, but vulnerabilities still exist for those who understand the underlying mechanics.
Trusted & Recommended Vendors
100% Verified + Escrow Support. Get your tools from:
For carders who want dumps, Linkable cards and more
Offers Premium Bank logins with Email Access and more..
Offers Premium Fullz, CC Logz and easy cashout tools
2. How is Money Transfer Carding Carried Out by Carders?
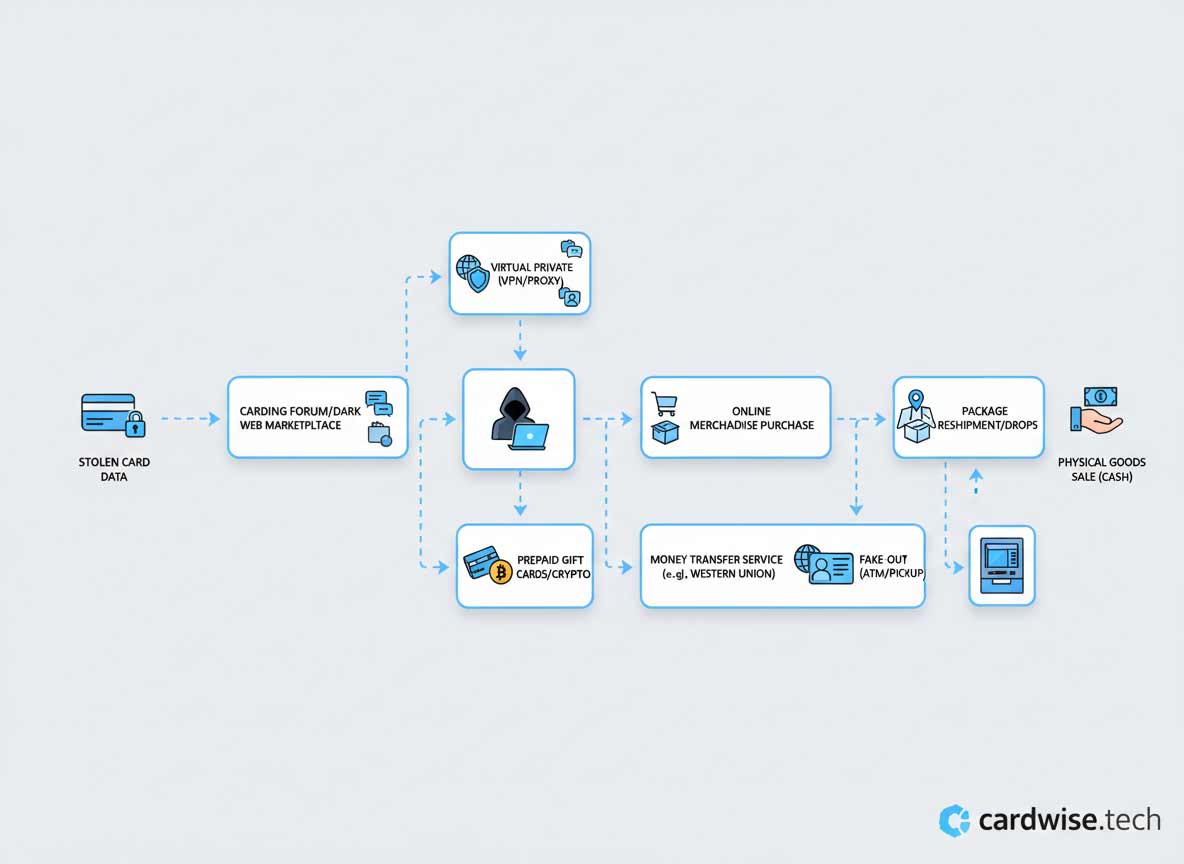
The process typically follows a structured workflow. First, the carder obtains high-quality card data from a reliable source. This data must include the card number, expiration date, CVV, and ideally the cardholder’s full personal information for address verification. Next, the carder identifies a money transfer service with weaker security protocols or a specific vulnerability. The carder then creates an account using synthetic or stolen identity information, carefully matching the cardholder’s details where necessary. The transfer is initiated, and the funds are sent to a receiving account often a money mule or a prepaid card that can be easily liquidated. The entire process requires careful attention to OPSEC, including the use of clean proxies, anti-detect browsers, and verified identity documents.
Also Read: Carding Websites 2026: Navigating the Ecosystem with Precision
CC Methods 2026 – Best Credit Card Cashout Methods That Work
3. Requirements for Money Transfer Carding
Successful money transfer carding requires several key components:
- High-Quality Card Data: Fresh, valid card information with matching personal details. The quality of your source directly impacts your success rate.
- Reliable Money Transfer Accounts: Accounts on platforms like Western Union, PayPal, or Cash App that are set up with matching or synthetic identities.
- Clean Proxies and OPSEC Tools: Residential proxies matching the cardholder’s location, anti-detect browsers, and VPNs are essential to avoid triggering fraud alerts.
- Money Mules or Receiving Accounts: Individuals or accounts that can receive and withdraw the transferred funds without raising suspicion.
- Knowledge of Platform-Specific Vulnerabilities: Each money transfer service has unique security measures. Understanding these is crucial for success.
- Patience and Testing: Successful carders test with small amounts before attempting larger transfers.
4. Top Carded Money Transfer Services in 2026
Different money transfer services offer varying levels of difficulty and reward. Here’s a breakdown of the most commonly targeted platforms.
Western Union Carding
Western Union remains a popular target due to its global reach and cash pickup options. However, its fraud detection has improved significantly. Success requires high-quality card data and careful attention to transfer limits and frequency. The cash pickup model makes it attractive for quick liquidation.
PayPal Carding
PayPal’s fraud detection is among the most sophisticated. Carding PayPal typically involves sending money to a verified account, then withdrawing to a bank account or card. The key is using card data that matches the PayPal account’s registered details. PayPal’s buyer protection can work against carders, so timing is critical.
Cash App Carding
Cash App has become increasingly popular due to its simplicity and lower security thresholds for smaller transactions. Carding Cash App involves linking a stolen card to an account and sending money to a receiving account. The platform’s instant transfer feature allows for rapid cashout.
Remitly Carding
Remitly specializes in international money transfers, often to countries with less stringent banking regulations. This makes it attractive for carders looking to move money across borders. The platform’s focus on remittance corridors can provide opportunities for those who understand specific country dynamics.
Skrill Carding
Skrill is an e-wallet that allows for easy money transfers and currency exchanges. Carding Skrill involves funding an account with stolen card data, then transferring funds to another e-wallet or bank account. Skrill’s verification process can be bypassed with quality synthetic identities.
Google Pay Carding
Google Pay’s integration with various financial services makes it a versatile target. Carding Google Pay typically involves adding a stolen card to a Google Pay account and using it for peer-to-peer payments or merchant transactions. The platform’s security relies heavily on device fingerprinting, making OPSEC crucial.
5. Steps for Carding Money Transfer Services
Follow these steps for a structured approach to money transfer carding:
Step 1: Source Quality Card Data Obtain fresh, valid card data from a trusted vendor. The data should include the card number, expiry date, CVV, and ideally the cardholder’s full name, address, and phone number.
Step 2: Set Up Your OPSEC Configure your anti-detect browser with a clean residential proxy matching the cardholder’s location. Clear all digital fingerprints and ensure your setup is clean.
Step 3: Create or Access a Money Transfer Account If creating a new account, use synthetic identity information that matches the cardholder’s details. If using an existing account, ensure it has a clean history.
Step 4: Initiate a Small Test Transfer Start with a small amount to test the card’s validity and the platform’s response. Monitor for any fraud alerts or verification requests.
Step 5: Scale Up Gradually Once the test transfer succeeds, gradually increase the transfer amount. Avoid sudden large transfers that might trigger manual review.
Step 6: Liquidate the Funds Have a receiving account or money mule ready to withdraw the funds immediately. The longer the money sits, the higher the risk of reversal.
6. Success Rate for Money Transfer Carding
The success rate for money transfer carding varies widely based on several factors: the quality of card data, the specific platform targeted, the carder’s OPSEC, and the current security landscape. In 2026, success rates for well-executed operations range from 30% to 60% for experienced carders. Beginners can expect lower rates, often below 20%, until they refine their techniques. The key to improving success rates is continuous learning and adaptation.
7. Benefits of Money Transfer to Carders
Money transfer carding offers several advantages over traditional goods-based carding:
- Direct Cash Conversion: No need to resell physical goods, reducing complexity and risk.
- Speed: Funds can be available within minutes to hours, compared to days for shipping.
- Global Reach: Money transfer services operate internationally, allowing for cross-border cashouts.
- Lower Detection Risk: Cash transactions are harder to trace than shipped goods.
- Scalability: Once a method is perfected, it can be repeated with different accounts and cards.
8. Best Offered Cashout Methods for Money Transfer Carding
Several cashout methods complement money transfer carding:
- Bank Account Transfers: Transferring funds directly to a bank account, then withdrawing via ATM or debit card.
- Prepaid Card Loading: Loading funds onto prepaid debit cards that can be used for purchases or ATM withdrawals.
- Cryptocurrency Purchases: Using money transfer funds to buy cryptocurrency, providing an additional layer of anonymity.
- Money Mule Networks: Using a network of individuals to receive and forward funds, distributing risk.
9. Common Mistakes and How to Avoid Them
- Using Low-Quality Card Data: Always source from reputable vendors. Cheap data is often dead or flagged.
- Neglecting OPSEC: Inadequate proxy or browser setup is the most common reason for failure.
- Rushing Large Transfers: Start small and scale up to avoid triggering fraud alerts.
- Ignoring Platform-Specific Rules: Each money transfer service has unique limits and verification requirements.
- Failing to Monitor Transactions: Regularly check the status of transfers and be prepared to act quickly if issues arise.
10. Pro Tips for Successful Money Transfer Carding
- Diversify Platforms: Don’t rely on a single money transfer service. Spread your operations across multiple platforms.
- Build a Network: Establish relationships with reliable money mules and other carders for information sharing.
- Stay Updated: Security measures change frequently. Regularly monitor forums for the latest methods and vulnerabilities.
- Keep Records: Document your successful and failed attempts to identify patterns and improve your approach.
- Have a Backup Plan: Always have an alternative cashout method in case your primary option fails.
11. Expert Insights: The Future of Money Transfer Carding
The future of money transfer carding will be shaped by increasing regulatory pressure and technological advancements. Biometric authentication, AI-driven fraud detection, and blockchain-based tracking are making traditional methods less effective. However, new opportunities will emerge as financial services expand into new markets and technologies. Carders who invest in understanding these systems and adapting their methods will continue to find success. The key is to stay ahead of the curve by continuously learning and innovating.
12. Summary & Actionable Takeaways
- Money transfer carding is a direct method of converting stolen card data into cash.
- Success requires high-quality card data, robust OPSEC, and platform-specific knowledge.
- Top services include Western Union, PayPal, Cash App, Remitly, Skrill, and Google Pay.
- Success rates range from 30% to 60% for experienced carders.
- Benefits include direct cash conversion, speed, and global reach.
- Common mistakes include poor OPSEC and rushing large transfers.
Your next step is to source high-quality card data from a trusted vendor. Without quality materials, even the best methods will fail.
Ready to start your money transfer carding journey? Source your materials from a trusted provider. Buy real CC from dumpseller.store.
Frequently Asked Questions (FAQ)
Q: What is money transfer carding? A: Money transfer carding is the process of using stolen credit card information to send money through digital money transfer services, then collecting that money through controlled accounts or money mules.
Q: What are the requirements for money transfer carding? A: Requirements include high-quality card data, clean proxies and OPSEC tools, money transfer accounts, money mules or receiving accounts, and knowledge of platform-specific vulnerabilities.
Q: What is the success rate for money transfer carding? A: Success rates vary from 30% to 60% for experienced carders, with beginners typically achieving lower rates until they refine their techniques.
Q: Which money transfer services are best for carding? A: Popular targets include Western Union, PayPal, Cash App, Remitly, Skrill, and Google Pay, each with different levels of difficulty and reward.
Q: How can I improve my success rate in money transfer carding? A: Improve your success rate by using high-quality card data, maintaining strong OPSEC, starting with small test transfers, and continuously learning from both successes and failures.
Trusted & Recommended Vendors
100% Verified + Escrow Support. Get your tools from:
For carders who want dumps, Linkable cards and more
Offers Premium Bank logins with Email Access and more..
Offers Premium Fullz, CC Logz and easy cashout tools
Q: Where can I buy real CCs for money transfer carding? A: For those looking for a reliable source, dumpseller.store is a trusted provider of quality CCs, dumps, and fullz suitable for money transfer carding.
